Skip to content
Category

Texas Personal Injury Articles & Resources – HLAW

Page 1 of 11 · 54 articles

Car owner running his hand along a freshly repaired SUV panel in a body shop while a technician holds a clipboard

Car Repaired but Worth Less? Diminished Value and Property Damage Claims After a DFW Wreck

By Luke A. Williams · Personal Injury

Short answer: In Texas, if another driver caused your wreck, you can generally seek diminished value from that driver's liability insurance. Diminished value is the loss in your car's market value even after it is fully repaired. Your own insurance policy is different. The Texas Supreme Court held in 2003 that the standard Texas personal auto policy does not require your insurer to pay diminished value when the car is fully and adequately repaired. Texas law also allows loss-of-use damages, such as a rental car, even when a vehicle is totaled. A property damage lawsuit generally must be filed within two years.

Car owner running his hand along a freshly repaired SUV panel in a body shop while a technician holds a clipboard

After a wreck on I-30, I-35W, or Highway 121, most people in Dallas-Fort Worth focus on getting the car repaired and back on the road. But a vehicle with an accident history often sells or trades in for less than an identical car that was never damaged, even when the repair is excellent. That gap is real money, and many people never ask for it.

At Howard Lotspeich Alexander & Williams, PLLC (HLAW), our Fort Worth trial lawyers handle car wreck and personal injury claims throughout Tarrant, Dallas, Denton, Collin, Johnson, and Parker counties. This guide explains what Texas law allows you to recover for damage to your vehicle, and how to document a diminished value and loss-of-use claim.

Key Takeaways

  • Third-party diminished value claims are allowed in Texas. The Texas Department of Insurance has stated that an insurer "may be obligated to pay a third party claimant for any loss of market value of the claimant's automobile, regardless of the completeness of the repair" (TDI Bulletin B-0027-00).
  • Your own collision coverage generally does not pay diminished value. In American Manufacturers Mutual Insurance Co. v. Schaefer, 124 S.W.3d 154 (Tex. 2003), the Texas Supreme Court held the standard policy "does not require payment for diminished value when a vehicle has been fully and adequately repaired" (Schaefer opinion).
  • UM/UIM coverage may be different. TDI's bulletin says an insurer may be obligated to pay its own policyholder for loss of market value under uninsured/underinsured motorist coverage, "regardless of the completeness of the repair."
  • Loss-of-use damages are recoverable even for a totaled car. The Texas Supreme Court held in 2016 that an owner of totally destroyed property "may recover loss-of-use damages in addition to the fair market value of the property immediately before the injury" (J&D Towing v. American Alternative Insurance Corp.).
  • You choose the body shop. An insurer settling a third-party property damage claim "may not require the third-party claimant to have repairs made by a particular repair person or facility" (Texas Insurance Code §1952.301).
  • The deadline is two years. Suits for injury to property generally must be filed within two years (Tex. Civ. Prac. & Rem. Code §16.003).

What Is Diminished Value?

Diminished value is the difference between what your vehicle was worth immediately before the wreck and what it is worth after repairs. Buyers and dealers often pay less for a vehicle with a reported accident, especially one with structural or frame damage, airbag deployment, or major body work.

There are generally three ways people describe it:

  • Inherent diminished value: the loss in market value caused by the accident history itself, even after a complete and proper repair. This is the most common type of claim.
  • Repair-related diminished value: additional lost value caused by poor or incomplete repairs, such as mismatched paint or parts that do not fit correctly.
  • Immediate diminished value: the drop in value right after the crash, before repairs. This mostly matters in calculating a total loss or a settlement before repair.

Texas courts have long measured damage to personal property using market value. When property is partially damaged, the general rule is "the difference in the market value immediately before and immediately after the injury to such property at the place where the damage was occasioned," as the Texas Supreme Court summarized in J&D Towing (opinion).

Who Pays Diminished Value in Texas?

Who pays depends on whose insurance you are claiming against.

Type of claim Is diminished value available? Source
Claim against the at-fault driver's liability insurance (third-party claim) Generally yes, regardless of the completeness of the repair TDI Bulletin B-0027-00
Claim under your own collision or comprehensive coverage (first-party claim) Generally no, when the car is fully and adequately repaired Schaefer (Tex. 2003)
Claim under your own UM/UIM coverage when the at-fault driver is uninsured or underinsured May be available, regardless of the completeness of the repair TDI Bulletin B-0027-00

Why your own collision coverage usually will not pay

In Schaefer, the policyholder's car was repaired and he did not dispute the quality of the repairs, but he claimed it was still worth $2,600 less. The Texas Supreme Court looked at the policy's "Limit of Liability" language, which caps the insurer's obligation at the lesser of the vehicle's actual cash value or the amount needed "to repair or replace" it. The court held that "repair" connotes "something tangible, like removing dents or fixing parts," and does not include compensation for "the market's perception that a damaged but fully and adequately repaired vehicle has an intrinsic value less than that of a never-damaged car" (Schaefer opinion).

The court left open other situations. It noted that if repairs were faulty, incomplete, or inadequate, the insurer might be liable for breaching its obligations under the policy. TDI's bulletin similarly says loss of market value can still be used to settle a dispute where a vehicle "was repaired properly but the vehicle still does not function as it did before the accident."

Why the at-fault driver's insurer is different

A claim against the at-fault driver is not a contract claim under your policy. It is a negligence claim, and the at-fault driver is responsible for the full harm caused to your property. That is why TDI's position is that a liability insurer may owe a third-party claimant for loss of market value "regardless of the completeness of the repair." In practice, many adjusters will not offer diminished value unless you ask for it and support it with evidence.

If you are still sorting out who caused the crash, our guide to how fault works in Texas personal injury cases explains the comparative fault rules that also apply to property damage.

Can You Get Paid for a Rental Car or Loss of Use?

Yes. Loss-of-use damages compensate you for the time you cannot use your vehicle. They are often measured by the reasonable cost of a comparable rental, or by lost income for a work vehicle.

For years, many Texas courts said loss-of-use damages were available only when a vehicle could be repaired, not when it was totaled. The Texas Supreme Court rejected that rule in J&D Towing, LLC v. American Alternative Insurance Corp., 478 S.W.3d 649 (Tex. 2016). The court held that "the owner of personal property that has been totally destroyed may recover loss-of-use damages in addition to the fair market value of the property immediately before the injury" (J&D Towing opinion).

The court also set limits. Loss-of-use damages must be foreseeable and directly traceable to the wreck, they cannot be speculative, and a plaintiff may not recover them for a period longer than reasonably needed to repair or replace the vehicle. As the court put it, permitting these damages "is not a license for unrestrained raids on defendants' coffers."

TDI's auto insurance guide explains how this usually works in practice: if another driver caused the accident, that driver's insurance company will pay for you to rent a car for the time it believes is reasonable for repairs, and "if the company totals your car, it might stop paying for the rental a few days after telling you." Tell the adjuster about parts delays or newly discovered damage, because the company may extend the rental.

What If Your Car Is Totaled?

If the cost to repair is close to or more than the car's value, the insurer will usually declare it a total loss. In a total loss, the measure is generally the fair market value immediately before the wreck, plus reasonable loss-of-use damages under J&D Towing. TDI explains that insurers pay actual cash value, which reflects depreciation, so a 10-year-old car is valued as a 10-year-old used car (TDI auto insurance guide).

To push back on a low total-loss valuation, gather listings for comparable vehicles in the DFW market with similar year, mileage, trim, and options. Also gather records of recent upgrades, new tires, or major maintenance. If you want to keep the car, TDI notes that the insurer will subtract its salvage value from the settlement.

How Do You Prove a Diminished Value Claim?

Insurers rarely pay diminished value without documentation. The strongest claims usually include:

  1. The final repair invoice, showing the extent of the damage and the parts replaced. Structural, frame, or airbag repairs tend to support larger claims.
  2. Photos of the damage before repair, from multiple angles.
  3. A written appraisal from an independent vehicle appraiser who explains the pre-accident value, the post-repair value, and how the difference was calculated.
  4. Dealer statements or trade-in offers showing what dealers will pay for the vehicle now compared with a similar vehicle without accident history.
  5. The vehicle's history report, if it shows the accident.
  6. The police crash report, to establish fault. Our article on how to get and use a Texas car wreck police report explains the process.

Send a written demand to the at-fault driver's insurer with these documents, and keep copies of every communication. If the adjuster uses a formula that produces a very low number, ask how it was calculated and respond with your own evidence. Our guide to insurance adjuster tactics in Fort Worth covers common approaches insurers use.

Do You Have to Use the Insurance Company's Body Shop?

No. Texas law protects your choice. In settling a third-party property damage claim, an insurer "may not require the third-party claimant to have repairs made by a particular repair person or facility" or require particular parts (Texas Insurance Code §1952.301(b)). For your own policy, §1952.302 prohibits an insurer or adjuster from stating or suggesting that you "must use a specific repair person or facility" or one on a preferred list for the repair to be covered.

Choosing a shop that documents its work thoroughly can also help a later diminished value claim, because detailed repair records show exactly what was damaged and replaced.

What Are the Deadlines for a Property Damage Claim in Texas?

A lawsuit for injury to property generally must be filed within two years after the claim accrues (Tex. Civ. Prac. & Rem. Code §16.003). The same two-year period applies to personal injury claims from the same wreck. Claims against government entities can involve much shorter notice deadlines. Our guide to the Texas statute of limitations explains the exceptions.

Insurers also have deadlines. TDI explains that a company must acknowledge your claim within 15 days, accept or reject it within 15 business days after receiving everything it needs (with up to 45 more days if it explains why), and pay within five business days after agreeing to pay (TDI auto insurance guide).

Should You Settle Your Property Damage Claim Separately From Your Injury Claim?

Often, yes. Many people resolve the vehicle claim first so they can get back on the road, while their injury claim continues as medical treatment progresses. Before signing anything, read the release carefully. A property damage release should be limited to property damage and should not release bodily injury claims. If the at-fault driver has only minimum coverage, the property damage limit is $25,000 under Texas's 30/60/25 requirement (TDI), and your own UM/UIM coverage may need to fill the gap.

Frequently Asked Questions

Can I claim diminished value from my own insurance company in Texas?

Generally not under collision or comprehensive coverage when the car is fully and adequately repaired. The Texas Supreme Court held in Schaefer (2003) that the standard Texas personal auto policy does not require it. A claim under your UM/UIM coverage may be different, and disputes over faulty or incomplete repairs are treated differently.

How much is a diminished value claim worth?

It depends on the vehicle's age, mileage, pre-accident value, and the severity of the damage. Newer, higher-value vehicles with structural damage tend to lose the most value. An independent appraisal and dealer trade-in comparisons are the best evidence of the actual loss.

Does the at-fault driver's insurance have to pay for my rental car?

If the other driver caused the wreck, that driver's insurer typically pays for a rental for the time reasonably needed to repair the car. Under J&D Towing, loss-of-use damages are also available when a vehicle is totaled, but only for a reasonable period to replace it.

What if the repair shop did a bad job?

Poor or incomplete repairs can increase your loss. In a first-party claim, Schaefer noted that an insurer might be liable for breaching its policy obligations if repairs are faulty, incomplete, or inadequate. Document the problems with photos and a second shop's written evaluation.

Do I need a lawyer for a property damage claim?

Many vehicle-only claims are resolved without a lawyer. If you were also injured, if the insurer denies fault, or if the vehicle had high value or serious damage, a lawyer can help coordinate the property and injury claims and make sure a release does not give up more than it should.

How long do I have to file a diminished value claim in Texas?

A lawsuit generally must be filed within two years of the wreck under Civil Practice and Remedies Code §16.003. It is best to start the claim right away, while repair records and appraisals are fresh.

Talk to a Fort Worth Car Wreck Lawyer

If another driver damaged your vehicle and hurt you or your family, you may be entitled to more than the repair bill. That can include lost market value, loss of use, and compensation for your injuries.

Call HLAW at (817) 993-9249 or contact us online for a free consultation about your Dallas-Fort Worth car wreck claim.

This article is for general informational purposes only and is not legal advice. Reading it does not create an attorney-client relationship. Laws change, and every case depends on its specific facts.
Read full article
Silver rental sedan with luggage in the open trunk after a rear-end crash with a pickup near a DFW airport

Hit by a Rental Car Driver in DFW? Who Pays After a Rental Car Crash in Texas

By Luke A. Williams · Personal Injury

Short answer: If a driver in a rental car hits you in Texas, the claim usually runs against the driver and the insurance that covers the driver, not the rental company. A federal law known as the Graves Amendment bars holding a rental company liable just because it owns the car. Rental companies can still be liable for their own negligence, such as renting a car with known defects. Texas law also gives you a way to sue an out-of-state renter who has already flown home.

Silver rental sedan with luggage in the open trunk after a rear-end crash with a pickup near a DFW airport

With two major airports, DFW International and Dallas Love Field, Dallas-Fort Worth sees a steady stream of out-of-town drivers on unfamiliar roads like the airport's spur highways, Highway 114, Highway 183, and I-635, often tired and relying on GPS. When one of them causes a crash, injured people usually face the same questions: Who pays? Does the rental company's insurance apply? What if the driver lives in another state?

At Howard Lotspeich Alexander & Williams, PLLC (HLAW), our Fort Worth trial lawyers handle personal injury claims throughout Tarrant, Dallas, Denton, Collin, Johnson, and Parker counties. This guide explains how rental car crash claims work in Texas, whether you were hit by a renter or were driving a rental yourself.

Key Takeaways

  • The Graves Amendment generally shields rental companies from owner-based liability. A company in the rental business "shall not be liable... by reason of being the owner of the vehicle" for harm arising from the renter's use, if there is "no negligence or criminal wrongdoing" by the company (49 U.S.C. §30106).
  • Direct negligence is a different story. Federal courts in Texas have held that the Graves Amendment bars vicarious liability but "does not preempt theories of direct liability" (N.D. Tex. 2025 opinion).
  • Texas minimum liability coverage is 30/60/25: $30,000 per person, $60,000 per crash for bodily injury, and $25,000 for property damage (Tex. Transp. Code §601.072).
  • Out-of-state drivers can still be sued here. The chair of the Texas Transportation Commission is the agent for service of process on a nonresident in a suit arising from a Texas collision (Tex. Civ. Prac. & Rem. Code §17.062).
  • Your own coverage may matter most. UM/UIM and PIP can fill gaps when the renter's coverage is low or missing.

Who Is Liable When a Rental Car Driver Hits You in Texas?

The starting point is the same as any Texas car wreck: the driver who caused the crash is responsible for the harm caused by their negligence. Texas assigns fault by percentage, and you can recover as long as you're not more than 50% responsible. Our guide to how fault works in Texas personal injury cases explains those rules.

What's different in a rental car case is the question of who else might be responsible, and whose insurance pays.

What the Graves Amendment says

Before 2005, some states made rental companies liable for their customers' crashes simply because the companies owned the cars. Congress ended that with the Graves Amendment. It provides that an owner that rents or leases a vehicle "shall not be liable under the law of any State... by reason of being the owner of the vehicle... for harm to persons or property that results or arises out of the use, operation, or possession of the vehicle during the period of the rental or lease," as long as the owner is "engaged in the trade or business of renting or leasing motor vehicles" and "there is no negligence or criminal wrongdoing on the part of the owner" (49 U.S.C. §30106(a)).

Courts in Texas apply this rule regularly. In a 2025 Dallas federal case involving a leased trailer, the court held that the Graves Amendment barred the plaintiff's vicarious liability and respondeat superior claim against the leasing company, while noting that the statute "does not preempt theories of direct liability, like negligent hiring and training" (N.D. Tex. 2025).

The law also has a carve-out for financial responsibility. It doesn't override state laws "imposing financial responsibility or insurance standards on the owner of a motor vehicle," or liability on rental businesses "for failure to meet the financial responsibility or liability insurance requirements under State law" (§30106(b)).

When Can a Rental Car Company Be Held Responsible?

Because the Graves Amendment protects only against liability based on ownership, a rental company can still be responsible for its own negligence. Potential claims include:

  • Negligent maintenance. Renting out a car with bad brakes, bald tires, or a known defect, including an unrepaired safety recall.
  • Negligent entrustment. Renting to someone the company knew, or should have known, was unlicensed, incompetent, or reckless.
  • Criminal wrongdoing by the company or its employees.

These claims are hard to win. Under Texas law, negligent entrustment requires proof of "(1) entrustment of a vehicle by the owner; (2) to an unlicensed, incompetent, or reckless driver; (3) that the owner knew or should have known to be unlicensed, incompetent, or reckless; (4) that the driver was negligent on the occasion in question; and (5) that the driver's negligence proximately caused the accident" (O'Donnell v. Diaz, N.D. Tex.). Federal courts applying Texas law have also said a company that entrusts a vehicle "has no duty to investigate a driver's competency when a valid, unrestricted driver's license is presented" (Marr v. Croxton, W.D. Tex.).

Causation is another hurdle. In Allways Auto Group v. Walters, the Supreme Court of Texas held that a dealership that gave a customer a loaner car wasn't liable when the customer drove drunk and caused a crash eighteen days later, because the loan was not a proximate cause of the crash (Tex. 2017).

In practice, the rental company is most often a defendant when there's evidence of a mechanical failure. That makes it critical to preserve the vehicle and its maintenance records before the company repairs, resells, or returns the car to the fleet.

Whose Insurance Pays After a Rental Car Crash?

Several layers of coverage may be involved, and the order in which they apply depends on the policies and the rental contract. Common sources include:

Coverage source What it may cover Notes
Renter's personal auto policy Liability for injuries the renter causes Many personal policies extend to rental cars; check the policy language
Rental company coverage Liability up to the limits the company provides Often limited; Texas minimums are 30/60/25 (§601.072)
Supplemental liability insurance bought at the counter Additional liability limits Only if the renter purchased it
Your own UM/UIM coverage Your injuries when the at-fault driver has no or too little insurance See our UM/UIM and PIP guide
Your own PIP Medical bills and lost income regardless of fault Covers the named insured, household members, and authorized drivers and passengers of the named insured's vehicle (Tex. Ins. Code §1952.151)
Credit card rental benefits Usually damage to the rental car itself Generally not a source of payment for your injuries

Because rental crashes often involve minimum or uncertain coverage, your own UM/UIM policy can become the most important coverage in the case. If the renter fled the scene or had no valid coverage, see our article on what to do after an uninsured driver accident in Fort Worth.

What If the Rental Car Driver Lives in Another State?

Many renters at DFW and Love Field are visitors who are back home within days. That doesn't put them beyond the reach of a Texas court. Under Section 17.062 of the Civil Practice and Remedies Code, the chair of the Texas Transportation Commission is an agent for service of process on a nonresident "in any suit against the person or agent that grows out of a collision in which the person or the person's agent is involved while operating a motor vehicle in this state." The same rule applies to a driver who lived in Texas at the time of the crash and later moved away.

Section 17.063 sets out the mechanics: a certified copy of the process must be served on the chair at least 20 days before the return date, and the chair then mails the papers to the nonresident by registered or certified mail (§17.063). In other words, an out-of-state renter can be sued in Tarrant or Dallas County, close to where the crash happened, rather than forcing you to file in another state.

International renters raise added issues, such as foreign insurance and serving papers abroad. Those cases call for early legal advice.

What If I Was Driving the Rental Car When I Got Hurt?

If you were driving or riding in a rental car and someone else caused the crash, your claim is against the at-fault driver, just like any other wreck. A few rental-specific issues often come up:

  • Damage to the rental car. The rental company may bill you or your insurer for repairs, loss of use, and administrative fees. Don't sign anything admitting responsibility for the crash.
  • The rental company's own crash report. Rental counters often ask you to fill out an incident form. Stick to the facts and keep a copy.
  • Your PIP and UM coverage. Depending on the policy terms, your own PIP and UM/UIM coverage may apply even though you were in a rental. Read the policy or have a lawyer review it.
  • Rideshare rentals. If you rented a car to drive for a rideshare app, different coverage rules may apply. See our guide to Uber and Lyft accidents.

What Should You Do After a Crash With a Rental Car in DFW?

  1. Call 911 and get a police report. In a crash with an out-of-town driver, the police crash report is often the best record of who was involved and their insurance.
  2. Photograph the rental car's identifiers. Photograph the plate, VIN sticker, and any barcode or fleet number, plus the renter's driver's license and insurance information.
  3. Get the renter's home address and phone number, and ask whether they bought coverage at the counter.
  4. Write down the rental company and location (for example, the airport rental center or a neighborhood branch).
  5. See a doctor promptly, even if you feel fine. Our article on seeing a doctor after a minor car accident explains why.
  6. Send a preservation letter early if a mechanical defect may have played a role, so the rental company keeps the car and its maintenance records.
  7. Be cautious with multiple adjusters. You may hear from the renter's insurer, the rental company's claims administrator, and your own carrier. Read about insurance adjuster tactics before giving a recorded statement.
  8. Watch the deadline. Most Texas injury lawsuits must be filed within two years. See our Texas statute of limitations guide.

Frequently Asked Questions

Can I sue the rental car company if its customer hit me?

Usually not just because the company owns the car. The Graves Amendment bars ownership-based liability for companies in the rental business, but it doesn't protect a company from liability for its own negligence or criminal wrongdoing (49 U.S.C. §30106). Evidence of poor maintenance or a known defect can support a direct claim.

Does the rental company's insurance cover my injuries?

It may, depending on the coverage the company provides and the rental agreement. Coverage is often limited, and Texas minimum liability limits are $30,000 per person and $60,000 per crash for bodily injury (Tex. Transp. Code §601.072). The renter's own auto policy or a supplemental policy bought at the counter may also apply.

The driver who hit me flew home to another state. Can I still sue in Texas?

Yes. Texas law makes the chair of the Texas Transportation Commission the agent for service of process on nonresident drivers involved in collisions in Texas (CPRC §17.062).

Is a rental company liable for renting to a bad driver?

Only in limited situations. A negligent entrustment claim requires proof that the company knew or should have known the driver was unlicensed, incompetent, or reckless (O'Donnell v. Diaz), and courts have said there is no duty to investigate further when a valid, unrestricted license is presented (Marr v. Croxton).

What if the renter didn't have enough insurance?

Your own uninsured/underinsured motorist coverage may pay the difference, up to your policy limits. PIP can also pay medical bills and lost income regardless of fault (Tex. Ins. Code §1952.151).

How long do I have to file a claim?

Most Texas personal injury claims must be filed within two years of the crash. Claims involving government vehicles can have much shorter notice deadlines.

Talk to a Fort Worth Car Wreck Lawyer

Rental car crashes add layers of insurance, out-of-state drivers, and federal law to an already stressful situation. HLAW can identify every available policy, preserve the vehicle evidence, and serve a driver who has already left Texas. Call (817) 993-9249 or contact us online for a free consultation.

This article is for general informational purposes only and is not legal advice. Reading it does not create an attorney-client relationship. Every case depends on its specific facts, and the laws discussed here may change.

Read full article
Injured worker with his arm in a sling reviewing pay records and bills at a kitchen table, hard hat on a nearby chair

Missed Work After a DFW Injury? How to Prove Lost Wages and Lost Earning Capacity in Texas

By Jesse Lotspeich · Personal Injury

Short answer: In a Texas personal injury case, you can recover the wages you've already lost and the loss of your future capacity to earn, but you have to prove both with evidence, not estimates. Texas law requires lost earnings to be presented as a net loss after federal income taxes. Courts let juries consider your past earnings, stamina, efficiency, ability to work with pain, and work-life expectancy when measuring future losses. Pay stubs, tax returns, employer statements, medical work restrictions, and, in bigger cases, vocational and economic experts are what turn a lost paycheck into a recoverable claim.

Injured worker with his arm in a sling reviewing pay records and bills at a kitchen table, hard hat on a nearby chair

After a wreck on I-30 or a fall at a Fort Worth job site, the bills that hurt most are often not the medical bills. They're the missed paychecks. Missed shifts, used-up PTO, a lost promotion, or a career you can no longer do are all real economic losses under Texas law, but insurance companies routinely discount them when they aren't documented well.

At Howard Lotspeich Alexander & Williams, PLLC (HLAW), our Fort Worth trial lawyers handle personal injury cases throughout Tarrant, Dallas, Denton, Collin, Johnson, and Parker counties. This guide explains how Texas law treats lost wages and lost earning capacity, what evidence works, and the mistakes that shrink these claims.

Key Takeaways

  • Two different claims. Past lost earnings cover income you've already missed. Loss of earning capacity covers your diminished ability to earn in the future, even if you were paid the same or more after the injury.
  • Net, after taxes. Evidence of lost earnings or earning capacity "must be presented in the form of a net loss after reduction for income tax payments" under federal income tax law (Tex. Civ. Prac. & Rem. Code §18.091).
  • Reasonable measurement in dollars. You must give the jury evidence "sufficient to permit a jury to reasonably measure earning capacity in monetary terms" (Big Bird Tree Service v. Gallegos, Tex. App.—Dallas 2012).
  • Lost wages are economic damages. Texas defines economic damages as compensation for "actual economic or pecuniary loss" (CPRC §41.001(4)).
  • PIP can help right away. Personal injury protection coverage pays "replacement of income lost as the result of the accident" for income producers, regardless of fault (Tex. Ins. Code §1952.151).

What Is the Difference Between Lost Wages and Lost Earning Capacity?

Texas law treats these as related but distinct damages.

Past lost earnings (lost wages) are the income you actually lost between the injury and trial or settlement: missed hours, missed shifts, unpaid leave, lost overtime, lost commissions, and lost bonuses that were reasonably certain.

Loss of earning capacity looks at something broader: your ability to earn money. Texas courts describe it as an assessment of the plaintiff's capacity to earn a livelihood before the injury and the extent to which the injury impaired that capacity. It "is not measured by what a person actually earned before an injury, but by the person's capacity to earn, even if he had never worked in that capacity in the past" (Tex. App.—Houston [1st Dist.] 2013).

That second point matters. Courts "have consistently upheld judgments for reduced earning capacity, even though the plaintiff was making as much or even more money after the injury than before," where pain, weakness, or diminished functional ability impaired the person's capacity to get and hold a job, or the duration, consistency, or efficiency of their work (Kelsey-Seybold Medical Group v. Roberts, Tex. App.—Houston [1st Dist.] 2024).

Past lost earnings Loss of future earning capacity
Time period Injury to trial or settlement After trial, for the rest of your work life
What it measures Income actually lost Diminished ability to earn
Typical proof Pay stubs, W-2s, tax returns, employer letter, timesheets Medical restrictions, vocational testimony, economist, past earnings history
Tax rule Net after federal income tax (§18.091) Net after federal income tax (§18.091)

How Do You Prove Lost Wages in a Texas Injury Claim?

For an hourly or salaried employee, the proof is usually straightforward, but it has to be complete:

  1. A doctor's work restriction. A note or record showing you were taken off work or placed on light duty, and for how long. Without it, insurers will argue you chose not to work.
  2. Pay records. Recent pay stubs and W-2s showing your rate, typical hours, and overtime history.
  3. An employer verification letter. A letter from HR or a supervisor confirming your position, pay rate, the dates you missed, and any lost overtime, bonuses, or promotion.
  4. Tax returns. Usually two to three years, especially if your income varies.
  5. PTO and sick leave records. If you used paid leave to cover missed days, document it.

What if I'm self-employed or a gig worker?

Self-employed claims require more proof, but they're recoverable. Courts recognize that "when the plaintiff seeks special damages for loss of earning capacity in a particular business, the amount of his earnings or the value of his services in that business must be shown with reasonable certainty" (Perez v. Perez, Tex. App.—Corpus Christi 2013). Useful evidence includes:

  • Schedule C or business tax returns for several years
  • 1099 forms and app earnings statements for rideshare and delivery drivers
  • Bank deposits, invoices, and canceled contracts or jobs you had to turn down
  • The cost of hiring someone to cover your work while you recovered
  • Testimony from regular customers or business partners

When income has been irregular, an accountant or economist can help show average earnings and what you would likely have earned during your recovery.

How Do Texas Courts Measure Lost Future Earning Capacity?

Future losses are uncertain by nature, and Texas law accepts that. "Proof of loss of earning capacity is always uncertain and is left largely to the discretion of the jury" (Big Bird Tree Service v. Gallegos). But the jury's award must rest on evidence, not speculation. Courts have said an award "must be based on something more than mere conjecture" (Durham Transportation Co., Tex. App.).

The Dallas Court of Appeals lists non-exclusive factors juries may consider: "evidence of past earnings, the plaintiff's stamina, efficiency, and ability to work with pain, and the plaintiff's work-life expectancy" (Big Bird Tree Service). Other Texas courts add "the weaknesses and degenerative changes that will naturally result from the plaintiff's injury" (Durham Transportation).

In practice, strong future-earnings claims usually include:

  • Treating doctor testimony on permanent restrictions (for example, no lifting over 20 pounds, no repetitive overhead work).
  • A vocational expert who explains which jobs you can still do and what they pay in the DFW labor market.
  • An economist who calculates the difference over your expected work life, adjusts for taxes as §18.091 requires, and reduces future amounts to present value.
  • Your own testimony and co-workers' testimony about how the injury affects your stamina and performance.

Will My Lost Wage Award Be Taxed?

Generally, damages for personal physical injuries aren't taxable as income under federal law, which is the reason for Texas's net-of-tax rule. Section 18.091(b) also requires the court to "instruct the jury as to whether any recovery for compensatory damages sought by the claimant is subject to federal or state income taxes" (CPRC §18.091). The practical effect: your lost earnings must be calculated on take-home pay, not gross pay. Tax questions about a specific settlement should go to a tax professional.

Can PIP Pay My Lost Income After a Car Wreck?

Yes, if you have it. Texas personal injury protection coverage pays, for an income producer, "replacement of income lost as the result of the accident," for expenses incurred within three years of the accident (Tex. Ins. Code §1952.151). Insurers aren't required to offer more than $2,500 per person in PIP, though many people buy more (§1952.153). The insurer must pay benefits no later than the 30th day after it receives satisfactory proof of the claim (§1952.156).

PIP applies regardless of fault, so it can help cover the gap while the liability claim is pending. Our guide to UM/UIM and PIP coverage explains how these policies fit together.

If you were hurt on the job, the rules may be different. Workers' compensation, or the lack of it with a non-subscriber employer, changes how lost income is handled. See our page on workplace accidents.

What Mistakes Hurt Lost Wage Claims?

  • Returning to work against medical advice, then trying to claim the time later.
  • Gaps in treatment, which insurers use to argue you were well enough to work.
  • Unreported cash income. If income wasn't reported on tax returns, it's very difficult to prove and can create other problems.
  • Posting on social media about physical activities or side jobs while claiming you can't work.
  • Giving the adjuster a recorded statement that downplays your limitations. Read about insurance adjuster tactics in Fort Worth.
  • Settling before you know your restrictions. If a surgeon hasn't released you, you may not yet know whether you can return to your trade.
  • Missing the deadline. Most Texas injury lawsuits must be filed within two years. See our Texas statute of limitations guide.

Lost earnings are only part of the picture. Our article on what compensation is available in a Texas personal injury lawsuit covers medical expenses, pain and suffering, and other damages. Noneconomic damages are defined separately in Texas law and include "physical pain and suffering, mental or emotional pain or anguish... physical impairment," and similar losses (CPRC §41.001(12)).

Frequently Asked Questions

Can I recover lost wages if I used PTO or sick days?

It may be possible. Paid leave you were forced to use because of the injury is a benefit you can no longer use for other purposes, and it is commonly presented as part of the earnings claim. Whether it is recoverable depends on the facts, so keep the payroll records showing the leave you used and the dates.

Can I claim lost earning capacity if I went back to the same job?

Possibly. Texas courts have upheld earning-capacity awards even when the plaintiff earned as much or more after the injury, where pain or diminished function impaired the ability to get and hold work or to work consistently and efficiently (Kelsey-Seybold v. Roberts).

Do I need an expert to prove future lost earnings?

Not always, but in cases involving permanent injury or a career change, a vocational expert and an economist are often the most persuasive way to give the jury a reasonable dollar measure, which the law requires (Big Bird Tree Service).

Are lost wages calculated before or after taxes in Texas?

After. Section 18.091 requires lost earnings and earning-capacity evidence to be presented as a net loss after federal income taxes (CPRC §18.091).

I'm self-employed. How do I prove what I lost?

Use tax returns, 1099s, invoices, bank deposits, and evidence of jobs you lost or turned down. The earnings or value of your services must be shown with reasonable certainty (Perez v. Perez).

Will my own insurance pay lost income while I wait?

If your auto policy includes PIP, it covers lost income for income producers regardless of fault, and the insurer must pay within 30 days of satisfactory proof (Tex. Ins. Code §§1952.151, 1952.156).

Talk to a Fort Worth Personal Injury Lawyer

If an injury has cost you paychecks, or your career, the way that loss is documented can make a substantial difference in what you recover. HLAW can gather your employment records, work with your doctors on restrictions, and bring in vocational and economic experts when needed. Call (817) 993-9249 or contact us online for a free consultation.

This article is for general informational purposes only and is not legal advice. Reading it does not create an attorney-client relationship. Every case depends on its specific facts, and the laws discussed here may change.

Read full article
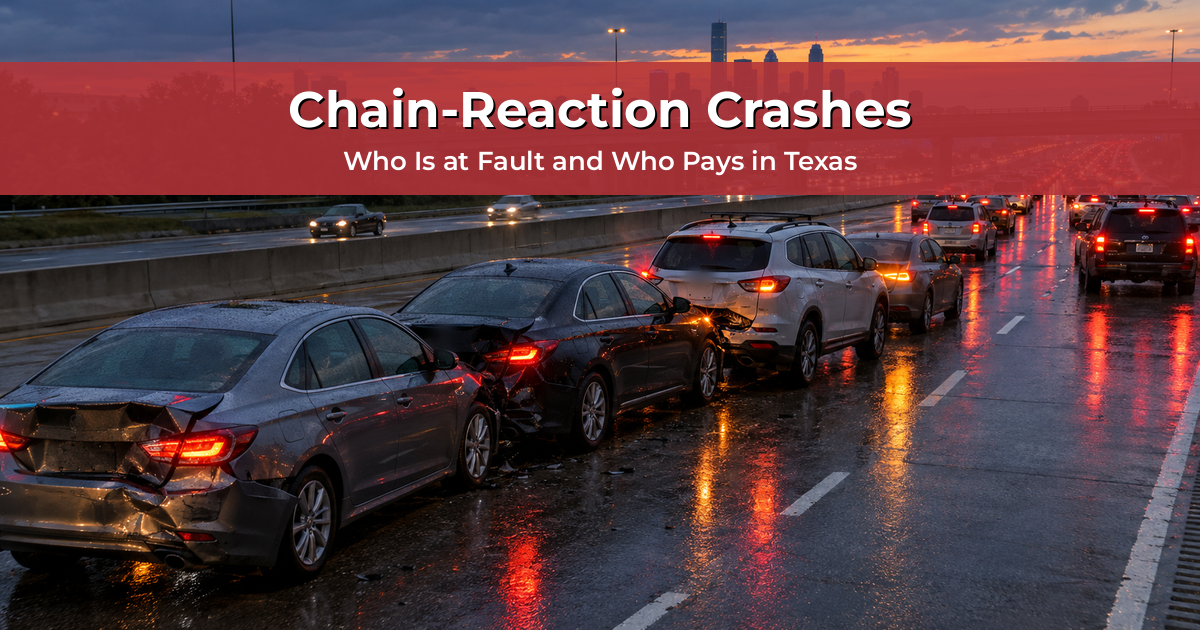
Chain-reaction rear-end crash involving several cars on a wet Dallas-Fort Worth freeway at dusk

Rear-Ended in a Chain-Reaction Crash on a DFW Highway? Who Is at Fault and Who Pays in Texas

By Jesse Lotspeich · Personal Injury

Short answer: In Texas, the driver who rear-ends you is usually, but not automatically, the one at fault. Texas law requires following drivers to keep an "assured clear distance," but courts hold that the mere fact of a rear-end collision does not prove negligence by itself. In a chain-reaction crash, a jury divides responsibility among every driver who contributed. You can recover as long as you are not more than 50% at fault, and any defendant found more than 50% responsible can be made to pay the entire judgment.

Chain-reaction rear-end crash involving several cars on a wet Dallas-Fort Worth freeway at dusk

Rear-end and chain-reaction crashes are part of daily life on DFW highways. Traffic on I-35W, I-30, I-20, Loop 820, LBJ (I-635), and Highway 121/183 can go from 70 mph to a dead stop in seconds, and when one driver doesn't stop in time, three, four, or five vehicles can end up in the same crash. In 2025, TxDOT recorded 30,433 reportable crashes in Tarrant County and 43,946 in Dallas County (TxDOT 2025 crashes and injuries by county).

At Howard Lotspeich Alexander & Williams, PLLC (HLAW), our Fort Worth trial lawyers handle personal injury claims across Tarrant, Dallas, Denton, Collin, Johnson, and Parker counties. This guide explains how Texas assigns fault in rear-end and multi-car crashes, what the other drivers' insurers will argue, and what you can do to protect your claim.

Key Takeaways

  • Following drivers have a statutory duty. Texas Transportation Code §545.062 requires a following driver to keep an "assured clear distance" so they can stop safely (Tex. Transp. Code §545.062).
  • A rear-end crash is evidence of negligence, not automatic proof of it. Texas courts, including the Fort Worth Court of Appeals, hold that the mere occurrence of a rear-end collision is not negligence as a matter of law (Campbell v. Perez).
  • Fault is divided by percentages. The jury assigns a percentage of responsibility to each claimant, defendant, settling person, and designated responsible third party (Tex. Civ. Prac. & Rem. Code §33.003).
  • The 51% bar applies. You can't recover if you are more than 50% responsible, and your recovery is reduced by your own percentage (§§33.001, 33.012).
  • Joint and several liability above 50%. A defendant found more than 50% responsible can be held liable for all recoverable damages (§33.013(b)).
  • Evidence disappears fast. Dash-cam footage, vehicle data, and witness memories can be lost within days, so early investigation matters.

Who Is at Fault in a Rear-End Collision in Texas?

Usually the following driver. Section 545.062(a) of the Transportation Code says a driver following another vehicle "shall... maintain an assured clear distance between the two vehicles so that, considering the speed of the vehicles, traffic, and the conditions of the highway, the operator can safely stop without colliding with the preceding vehicle." In other words, the law expects you to leave enough room to stop for whatever happens ahead, including a sudden slowdown on I-30 at rush hour.

But Texas doesn't treat a rear-end collision as automatic liability. Courts have said for decades that "the mere occurrence of a rear-end collision is some evidence of negligence of the rear-ending driver but is not negligence as a matter of law," and that the plaintiff must prove "specific acts of negligence on the part of the following driver as well as proximate cause" (Campbell v. Perez, Tex. App.—Fort Worth 2015). Courts have also held that a violation of §545.062 doesn't create negligence per se. It sets the same reasonable-care standard as the common law and leaves the question to the jury (Arn v. Stuart, Tex. App.—Austin 2010).

That's why "they hit me from behind" is the start of a case, not the end of it. Specific acts of negligence commonly proven in rear-end cases include:

  • Following too closely for the speed, traffic, or weather
  • Failing to keep a proper lookout
  • Speeding or driving too fast for conditions
  • Failing to brake in time
  • Texting or reading messages while driving, which is a separate traffic offense in Texas (§545.4251)
  • Driving while intoxicated

When the lead driver can share fault

The defense will look for ways to shift blame to you. Common arguments include:

  • You stopped suddenly and without reason, or "brake-checked" the other driver
  • You cut in front of the following driver and then slowed down
  • Your brake lights didn't work
  • You were stopped in a travel lane without hazard lights

In one Austin case cited often by Texas courts, a jury that believed the lead driver stopped "abruptly" and without explanation was allowed to find the following driver not negligent (Hall v. Moore). These arguments are fact-specific, and evidence like dash-cam video and vehicle data often decides them.

How Is Fault Divided in a Chain-Reaction Crash?

A chain-reaction crash (sometimes called a multi-car pileup) happens when one impact pushes vehicles into each other. A typical DFW example: Car C slams into Car B, which is pushed into Car A, which was stopped in traffic on Loop 820. Sometimes there are two separate impacts: Car B stops in time, and then Car C hits Car B and shoves it into Car A.

Texas handles these crashes under the proportionate responsibility statute, Chapter 33 of the Civil Practice and Remedies Code:

Rule What it means for you Source
Percentages for everyone The jury assigns a percentage of responsibility to each claimant, each defendant, each settling person, and each designated responsible third party §33.003
51% bar You can't recover if your share is greater than 50% §33.001
Reduction for your share Your damages are reduced by your percentage of responsibility §33.012(a)
Several liability Each defendant generally pays only its own percentage §33.013(a)
Joint and several above 50% A defendant found more than 50% responsible can be liable for all recoverable damages §33.013(b)
Responsible third parties A defendant can ask to put a non-party, such as a driver who fled, on the verdict form, generally by motion at least 60 days before trial §33.004

For a broader look at these rules, see our article on how fault works in Texas personal injury cases.

Why the percentages matter so much

Suppose you're in Car A, stopped in traffic, and you suffer $200,000 in damages. A jury finds Car C's driver 70% responsible and Car B's driver 30% responsible, and assigns you 0%. Because Car C's driver is over 50%, that driver is jointly and severally liable and can be made to pay the full $200,000. If the jury had instead split fault 50/50 between B and C, neither would be over 50%, and each would generally owe only $100,000. That matters if one of them has only minimum insurance.

Which impact caused which injury?

Multi-impact crashes raise a causation question: which collision caused which injury? The insurer for the first car may argue your injuries came from the second impact, and vice versa. Accident reconstruction, vehicle damage photos, airbag control module (event data recorder) downloads, and medical testimony are often needed to connect specific injuries to specific impacts. A thorough police crash report helps, but reports are often incomplete in multi-car crashes, especially when officers arrive after the vehicles have been moved.

What Defenses Will the Insurance Companies Raise?

Beyond blaming the lead driver, expect these arguments:

  1. Sudden emergency. Texas juries can be instructed that a driver confronted with an emergency "arising suddenly and unexpectedly," which the driver didn't cause, isn't negligent if the driver responded as a reasonably prudent person would (Dillard v. Texas Electric Cooperative, quoting the Texas Pattern Jury Charge). Drivers sometimes claim a car cut them off or debris appeared in the road.
  2. Unavoidable accident. This instruction tells jurors that an occurrence may not have been caused by any party's negligence, and it is most often raised with fog, ice, wet pavement, or obstructed views (Dillard). The Supreme Court of Texas approved its use in a rear-end crash with a car stopped on the blind side of an overpass in Reinhart v. Young, 906 S.W.2d 471 (Tex. 1995).
  3. Phantom driver. The defense may blame an unidentified vehicle that caused the chain reaction and then left. Your own uninsured motorist coverage may matter here. Our guide to UM/UIM and PIP coverage explains how it works.
  4. Minimal damage, minimal injury. Insurers often argue that low bumper damage means no real injury. Medical records, treatment consistency, and expert testimony answer that argument.

Wet pavement doesn't excuse following too closely. Section 545.062 expressly requires drivers to consider "the conditions of the highway." Drivers who know the road is wet are expected to leave more room. A police report that marks "following too closely" helps, but it is not conclusive. In one Texas case, the jury found no negligence despite that notation (Smith v. Central Freight Lines), which is why independent evidence matters.

What Evidence Wins Rear-End and Pileup Cases?

The strongest claims are built in the first few weeks:

  • Dash-cam and phone video. Your own camera, other drivers' cameras, and rideshare or commercial fleet cameras. Our article on dashcam footage after a Texas car accident explains how to preserve it.
  • Traffic and business cameras. TxDOT and city traffic cameras, toll gantry systems, and nearby business security cameras. Many are overwritten quickly, so preservation requests must go out fast.
  • Event data recorders. Most modern vehicles record speed, braking, and throttle data in the seconds before a crash.
  • Cell phone records. If distraction is suspected, phone records can show texting or app use at the moment of impact.
  • Commercial vehicle data. If a truck or delivery van was involved, electronic logging devices, telematics, and driver files are critical. See our 18-wheeler and commercial truck crash guide.
  • Witness statements. Independent witnesses are especially valuable in chain reactions, where each driver tends to blame the next.

What Should You Do After a Rear-End or Chain-Reaction Crash in DFW?

  1. Get to safety and call 911. On a highway, stay in your vehicle with your seatbelt on if it isn't safe to get out.
  2. Photograph every vehicle. Take pictures of each vehicle's damage, its position, its license plate, and the driver's insurance card.
  3. Get names and contact information for every driver and witness. In a chain reaction, you may have claims against more than one driver.
  4. Don't apologize or guess about fault. Stick to the facts.
  5. Get medical care promptly. Neck, back, and head injuries from rear impacts often get worse over the following days.
  6. Save your dash-cam footage immediately. Many cameras record over old footage in a loop.
  7. Be careful with adjusters. In a multi-car crash, several insurers may call you, each hoping to pin blame on someone else. Read about insurance adjuster tactics in Fort Worth before giving a recorded statement.
  8. Watch the deadline. Most Texas injury lawsuits must be filed within two years. If a government vehicle was involved, the notice deadline can be as short as six months. See our Texas statute of limitations guide.

Frequently Asked Questions

Is the driver who rear-ends you always at fault in Texas?

No, but usually. Texas law requires following drivers to keep an assured clear distance (§545.062), and a rear-end crash is some evidence of negligence. Still, courts hold it isn't negligence as a matter of law, so you must prove specific negligent acts and causation (Campbell v. Perez).

Who pays in a three-car chain-reaction crash?

Each driver who contributed pays their percentage of responsibility, and any driver found more than 50% at fault can be made to pay the full judgment (§33.013). Often the last car in the chain bears most of the responsibility, but not always. Middle drivers who were also following too closely can share fault.

I was in the middle car. Can I be sued?

Yes. If you were pushed into the car ahead after being hit, the evidence often shows you weren't at fault for that impact. But if you hit the car ahead first and were then struck from behind, you may share responsibility for the first impact. Each impact is analyzed separately.

Can I recover if I was partly at fault?

Yes, as long as you are not more than 50% responsible. Your damages are reduced by your percentage (§§33.001, 33.012).

What if the driver who started the chain reaction drove away?

You may be able to make a claim under your uninsured motorist coverage, and the remaining defendants may try to designate the missing driver as a responsible third party (§33.004). Report the crash to police immediately and preserve any video.

Does rain or ice excuse a rear-end crash?

Not by itself. The assured-clear-distance rule expressly considers "the conditions of the highway" (§545.062), so drivers are expected to leave more room in bad weather. A defendant may still ask for an unavoidable-accident instruction if the evidence supports it.

Talk to a Fort Worth Car Wreck Lawyer

Rear-end and chain-reaction crashes look simple, but the fault fight between multiple drivers and insurers can be complicated, and evidence disappears quickly. HLAW can preserve video and vehicle data, identify every responsible driver and policy, and build the proof Texas law requires. Call (817) 993-9249 or contact us online for a free consultation. You can also read more about what compensation is available in a Texas personal injury lawsuit.

This article is for general informational purposes only and is not legal advice. Reading it does not create an attorney-client relationship. Every case depends on its specific facts, and the laws discussed here may change.

Read full article
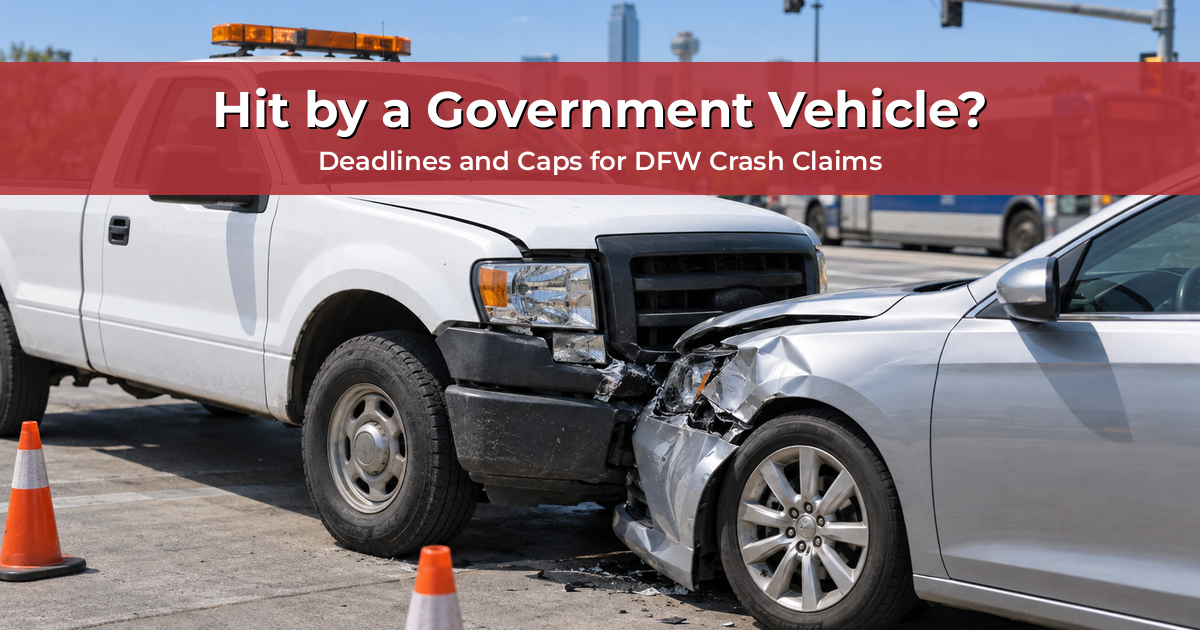
White city utility pickup truck with an amber light bar after a collision with a silver sedan at a DFW intersection, with orange traffic cones

Hit by a City Truck, Police Car, or DART Bus in DFW? Texas Tort Claims Act Deadlines and Damage Caps

By Jesse Lotspeich · Personal Injury

Short answer: If a city truck, police car, county vehicle, school bus, or DART or Trinity Metro bus hits you in Dallas-Fort Worth, you can usually still recover damages, but the Texas Tort Claims Act changes the rules. You generally must give the government written notice within six months (Fort Worth and Arlington require notice within 180 days under their city charters), and the government's liability is capped at $100,000 to $250,000 per person, depending on the type of entity. If the notice deadline passes, the claim can be thrown out even though the two-year statute of limitations hasn't run, so act quickly.

White city utility pickup truck with an amber light bar after a collision with a silver sedan at a DFW intersection, with orange traffic cones

Every week, Dallas-Fort Worth drivers share the road with garbage trucks, water department pickups, police cruisers, fire apparatus, TxDOT maintenance crews, school buses, and hundreds of DART and Trinity Metro buses. When one of those vehicles causes a crash, many people assume the claim works like any other car wreck. It doesn't. Government entities are protected by immunity unless the Legislature has waived it, and the waiver comes with short deadlines, damage caps, and procedural traps that don't apply to a claim against a private driver.

At Howard Lotspeich Alexander & Williams, PLLC (HLAW), our Fort Worth trial lawyers handle personal injury claims across Tarrant, Dallas, Denton, Collin, Johnson, and Parker counties, including claims against cities, counties, and transit agencies. This guide explains how a government-vehicle claim works in Texas, what deadlines apply in DFW, and the mistakes that most often sink these claims.

Key Takeaways

  • The Texas Tort Claims Act waives immunity for motor-vehicle crashes. A governmental unit can be liable when an employee acting within the scope of employment negligently operates a motor-driven vehicle (Tex. Civ. Prac. & Rem. Code §101.021).
  • Notice is due fast. State law requires notice within six months (§101.101), and city charters can set their own periods. Fort Worth and Arlington require 180 days, and Dallas requires six months.
  • Missing notice can end the case. Texas law makes statutory prerequisites, including notice, jurisdictional in suits against a governmental entity (Tex. Gov't Code §311.034).
  • Damages are capped. Cities and the state are capped at $250,000 per person and $500,000 per occurrence. Counties, school districts, and transit authorities like DART and Trinity Metro are capped at $100,000 per person and $300,000 per occurrence (§101.023).
  • Emergency responses get extra protection. If the officer or firefighter was responding to an emergency, the claim generally requires proof that they broke the law governing emergency driving or acted recklessly (§101.055).
  • Who you sue matters. Suing the employee instead of the agency, or suing both, can trigger the Act's election-of-remedies rules (§101.106).

Can You Sue the Government After a Car Wreck in Texas?

Yes, in many cases. Texas governmental entities are generally immune from suit, but the Texas Tort Claims Act carves out a limited waiver. Under Section 101.021, a governmental unit is liable for property damage, personal injury, and death caused by the negligence of an employee acting within the scope of employment if the harm "arises from the operation or use of a motor-driven vehicle or motor-driven equipment" and the employee would be personally liable under Texas law.

In plain English: if a city employee runs a red light on Lancaster Avenue in a city truck, or a county deputy rear-ends you on Loop 820 while driving to an ordinary call, the government can be held responsible the same way a private employer would be, subject to the limits explained below.

The motor-vehicle waiver covers most of the government vehicles you see in DFW:

  • City vehicles: police cars, fire trucks, ambulances, sanitation trucks, water and street-maintenance trucks, code-compliance cars
  • County vehicles: sheriff's patrol cars, road and bridge equipment, county-owned vans
  • State vehicles: TxDOT trucks and maintenance equipment, Department of Public Safety (DPS) trooper cars
  • School buses and district vehicles. For school districts, the Tort Claims Act applies only to claims involving motor vehicles (§101.051), so a bus crash is one of the few injury claims that can go forward against a district.
  • Public transit: DART buses and light rail in Dallas County, and Trinity Metro buses, TEXRail, and on-demand vehicles in Tarrant County

What Is the Deadline to File a Claim Against a City or County in DFW?

This is the most important section of this guide. Under Section 101.101(a), a governmental unit is entitled to receive notice of a claim no later than six months after the incident. The notice must reasonably describe the injury or damage, the time and place of the incident, and the incident itself. Section 101.101(b) also ratifies city charter provisions that set their own notice periods.

Here is how that plays out in the largest DFW cities and agencies:

Entity Notice deadline Damage cap (bodily injury) Source
City of Fort Worth 180 days, filed with the City Council (good-cause exception for late filing) $250,000 per person / $500,000 per occurrence Fort Worth City Charter, Ch. XXVII §25
City of Dallas Six months, written notice stating when, where, and how the injury occurred and the damages claimed $250,000 / $500,000 Dallas City Charter, Ch. XXIII §1
City of Arlington 180 days, filed with the City Secretary, plus a 90-day wait before suit $250,000 / $500,000 Arlington City Charter, Art. X §6
Counties, school districts, DART, Trinity Metro Six months under state law (check for any agency-specific rules) $100,000 / $300,000 §101.023(b)
State agencies (TxDOT, DPS) Six months $250,000 / $500,000 §101.023(a)

Every DFW suburb, including Grand Prairie, Irving, Mansfield, Keller, Southlake, and North Richland Hills, has its own charter, and some set different notice requirements. Always check the specific charter for the city whose vehicle was involved, and when in doubt, give notice well inside the shortest possible window.

Why the notice deadline is so dangerous

The general Texas deadline to file an injury lawsuit is two years (see our guide to the Texas statute of limitations). Many people relax because they think they have two years. But in a government case, the notice clock runs out long before then. And because Government Code §311.034 makes statutory prerequisites to suit, "including the provision of notice," jurisdictional, a government defendant can raise late notice to have the case dismissed outright.

What about "actual notice"?

Section 101.101(c) excuses formal notice if the governmental unit had actual notice that someone was injured or property was damaged. Don't count on it. Texas courts read actual notice narrowly, requiring the government's subjective awareness of the injury and its own possible fault. In one Tarrant County case, the Second Court of Appeals reviewed whether a police crash report gave the City of Arlington actual notice and found the city's evidence couldn't be deciphered (City of Arlington v. Evans). That kind of uncertainty is exactly why a formal written notice, sent early, is the safer path.

How Much Can You Recover From a Government Entity?

The Act caps the government's liability, and the cap depends on the type of entity (§101.023):

  • State government (TxDOT, DPS, state universities): $250,000 per person and $500,000 per occurrence for bodily injury or death; $100,000 per occurrence for property damage.
  • Municipalities (Fort Worth, Dallas, Arlington, and other cities): $250,000 per person and $500,000 per occurrence; $100,000 per occurrence for property damage.
  • Other local government (counties, school districts, transit authorities): $100,000 per person and $300,000 per occurrence; $100,000 per occurrence for property damage.

The Act also does not allow exemplary (punitive) damages (§101.024).

DART and Trinity Metro bus crashes

DART and Trinity Metro are regional transportation authorities, and Texas courts treat them under the $100,000-per-person local-government cap. The Dallas Court of Appeals applied that cap to a judgment against DART in Dallas Area Rapid Transit v. Morris. Many transit buses are actually operated by private contractors, but Transportation Code §452.056(d) limits a contractor performing the authority's function to the same liability the authority would have. In a Fort Worth bus case, the Supreme Court of Texas held that the transit authority and its operating contractors were cumulatively limited to a single $100,000 cap (Fort Worth Transportation Authority v. Rodriguez).

Finding other sources of recovery

Because the caps can be far below the true value of a serious injury, a careful investigation looks for every other responsible party and every available coverage:

  • Other drivers. Multi-vehicle crashes often involve a private driver who shares fault and whose insurance isn't capped.
  • Private contractors outside the transit statute. A private company doing city road work, for example, is not automatically protected by the transit-authority rule.
  • Your own coverage. Personal injury protection (PIP) pays regardless of fault, and depending on your policy language, other coverages may help. Our article on UM/UIM and PIP auto insurance explains how these coverages work.
  • Comparative fault. Texas's proportionate-responsibility rules still apply, so the government will try to shift blame to you. Our explainer on how fault works in Texas injury cases covers the 51% bar.

What If a Police Car or Fire Truck Hit You During an Emergency?

This is where many claims against cities are won or lost. Section 101.055(2) says the Act does not apply to a claim arising from an employee's action "while responding to an emergency call or reacting to an emergency situation" if the action complied with the laws applicable to emergency action or, absent such a law, if the action was not taken "with conscious indifference or reckless disregard for the safety of others."

The Supreme Court of Texas has set a high bar here. In City of San Antonio v. Maspero, a 2022 police-pursuit case, the Court held the emergency exception applied. It found that the officer's alleged violations of internal department policy weren't violations of "laws and ordinances," and that the family hadn't raised a fact issue of recklessness (Texas Supreme Court opinion summary). Reckless disregard requires more than a momentary lapse in judgment.

That doesn't mean emergency-vehicle claims are hopeless. It means the evidence has to be gathered quickly and thoroughly:

  1. Was the officer actually responding to an emergency, or driving to a routine call or back to the station?
  2. Were lights and sirens activated, and when?
  3. How fast was the vehicle going, and what were the traffic, visibility, and intersection conditions?
  4. Did the driver slow down at intersections and red lights, as Texas law generally requires of emergency drivers?
  5. What do dash-cam, body-cam, 911 audio, and computer-aided dispatch (CAD) records show?

Much of this evidence is in the government's own hands, and retention schedules vary. A prompt preservation letter and public-information requests are often the difference between a provable claim and a dismissed one. Our guide on dashcam footage after a Texas car accident explains why video evidence matters so much.

Should You Sue the Driver or the Government Agency?

Usually the agency, and the choice has permanent consequences. Under the Act's election-of-remedies provision (§101.106):

  • Filing suit under the Act against the governmental unit "immediately and forever bars" suit against the individual employee for the same subject matter.
  • Filing suit against the employee bars suit against the governmental unit unless the unit consents.
  • If both are sued, the employee must be dismissed on the government's motion.
  • If the employee was acting within the general scope of employment, a suit against the employee is treated as an official-capacity suit and must be refiled against the governmental unit within 30 days of a motion, or it will be dismissed.

Naming the wrong defendant can waste the limited time you have, or forfeit the claim. This is a technical area where getting it right at the outset matters.

What Should You Do After a Crash With a Government Vehicle in DFW?

  1. Call 911 and get a police report. Ask for the officer's name and report number. If the at-fault vehicle was a police car, a supervisor or another agency may investigate. Our article on reading a car wreck police report explains what to check.
  2. Record the vehicle details. Note the unit or fleet number on the vehicle, the department name, the route number for a bus, and the time and location. Photograph everything if it is safe to do so.
  3. Get witness names. Passengers on a bus, nearby drivers, and business employees often see what happened.
  4. Get medical care right away. Gaps in treatment are used to argue an injury wasn't serious.
  5. Calendar the shortest possible notice deadline. Assume 180 days for a Fort Worth or Arlington city vehicle and six months for most others, and don't wait until the end.
  6. Send written notice that complies with the Act and any charter. It should describe the injury, the time and place, and how the incident happened. Fort Worth's charter also asks for the amount of damages, the settlement amount, the claimant's address, and witness names. Fort Worth publishes a risk-management claim form, and Dallas publishes a notice of claim form.
  7. Be careful with the government's adjuster. Many cities and counties are handled by risk-management departments or risk pools that investigate to limit payouts. Read our tips on insurance adjuster tactics before giving a recorded statement.
  8. Talk to a lawyer early. Preservation letters, public-information requests, the right defendant, and a compliant notice all need to happen inside the notice window.

Common Mistakes That Sink Government-Vehicle Claims

  • Assuming you have two years. The notice deadline is typically six months or 180 days.
  • Treating a phone call as notice. Calling the bus agency's customer service line or the city's 311 line usually isn't written notice under the Act or a charter.
  • Sending notice to the wrong office. Charters often specify who receives notice (for example, the City Council in Fort Worth or the City Secretary in Arlington). Older Texas cases have rejected notice delivered to the wrong official.
  • Leaving out required details. A notice that doesn't describe the injury, the time and place, and the incident may be challenged.
  • Suing the employee alone. This can trigger the election-of-remedies bar described above.
  • Ignoring other parties. Failing to investigate a private driver or contractor can leave money on the table when the government's cap is low.

Frequently Asked Questions

How long do I have to file a claim after being hit by a Fort Worth city vehicle?

The Fort Worth City Charter requires written notice to the City Council within 180 days of the injury, unless good cause is shown for a late filing (Fort Worth City Charter, Ch. XXVII §25). The lawsuit itself generally must be filed within two years. Don't rely on the good-cause exception; file well before the 180th day.

Can I sue DART or Trinity Metro if a bus hit my car?

Generally yes, if the injury arose from the negligent operation of the bus. These transit authorities are treated as local governmental units, so the Tort Claims Act's six-month notice rule and its $100,000-per-person cap generally apply (§101.023; Fort Worth Transportation Authority v. Rodriguez).

What if I was a passenger on the bus when it crashed?

Passengers can bring claims too, and the same notice rules and caps generally apply. Texas courts have recognized that a common carrier like DART owes its passengers a high degree of care (Dallas Area Rapid Transit v. Morris).

Can I get punitive damages from the city?

No. The Texas Tort Claims Act does not authorize exemplary damages (§101.024).

A police officer hit me while running lights and sirens. Do I have a case?

Possibly, but it is harder. Under the emergency exception, you generally need evidence that the officer violated the laws governing emergency driving or acted with conscious indifference or reckless disregard for public safety (City of San Antonio v. Maspero). The facts, especially video and dispatch records, decide these cases.

What if a TxDOT truck caused my wreck on I-35W or I-30?

TxDOT is a state agency, so the state-government cap of $250,000 per person and $500,000 per occurrence applies, and notice is due within six months (§101.023(a); §101.101). If a private contractor was doing the work, there may be a separate claim against that company.

Talk to a Fort Worth Injury Lawyer Before the Notice Deadline Passes

A crash with a government vehicle is a race against a short clock. HLAW can identify the right government entity, calculate the correct notice deadline, send a compliant notice, preserve video and dispatch records, and look for every other source of recovery beyond the government's cap. Call (817) 993-9249 or contact us online for a free consultation.

This article is for general informational purposes only and is not legal advice. Reading it does not create an attorney-client relationship. Laws and city charters change, and every case depends on its specific facts.

Read full article

Speak with a Fort Worth attorney

Call (817) 993-9249 or send us a message to discuss your case.